The 50/30/20 Budget Explained
Budgeting can become complicated surprisingly quickly. Some systems ask you to create dozens of spending categories, track every purchase, and decide exactly how much you’re allowed to spend on everything from groceries to coffee. The 50/30/20 budget takes a simpler approach.
By Bridger Garcia on October 3, 2026
Getty Images
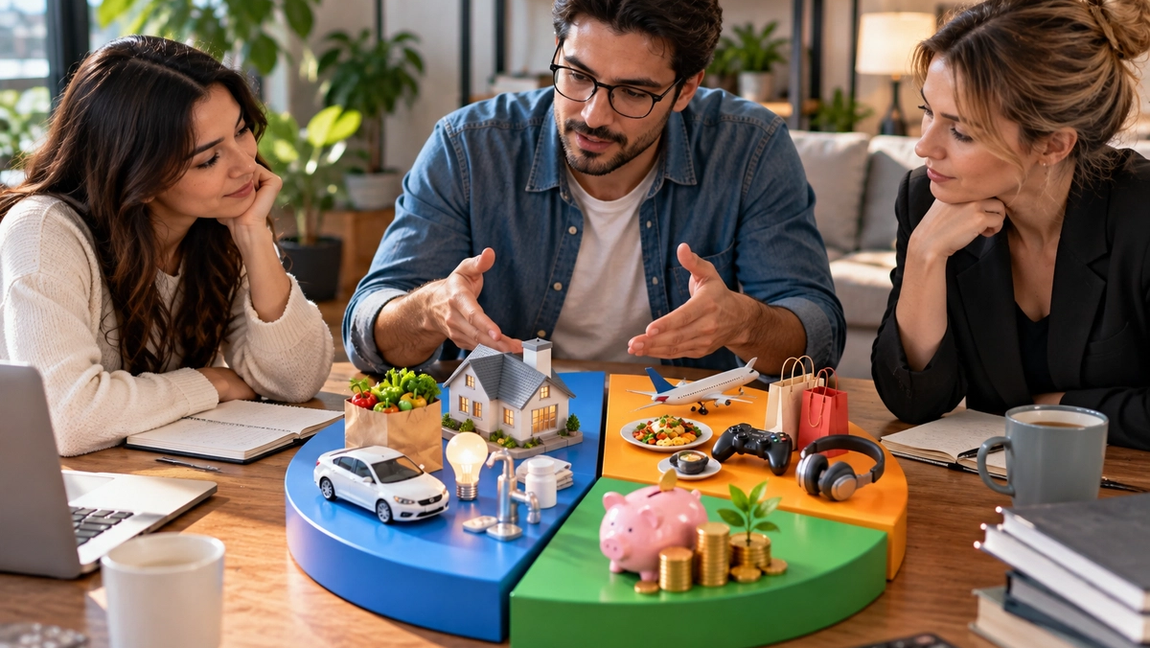
Budgeting can become complicated surprisingly quickly. Some systems ask you to create dozens of spending categories, track every purchase, and decide exactly how much you’re allowed to spend on everything from groceries to coffee. The 50/30/20 budget takes a simpler approach. Instead of managing every expense separately, you divide your after-tax income into three broad categories: 50% for needs, 30% for wants, and 20% for savings and certain financial goals. It’s not a perfect formula for every household, but it can provide a useful starting framework for understanding where your money is going.
Put roughly 50% toward your needs
The first category covers expenses you genuinely need to maintain your basic life and meet financial obligations. This commonly includes housing, utilities, groceries, basic transportation, insurance, necessary healthcare, childcare, and minimum required debt payments. If your monthly take-home income is $4,000, the 50/30/20 framework would allocate approximately $2,000 to this category. The distinction between a need and a want isn’t always obvious. You may need a phone, for example, but you probably don’t need the most expensive phone and unlimited premium plan available. You may need transportation, but there can be a difference between the cost of reliable transportation and the cost of a luxury vehicle. The 50% figure is best understood as a guideline rather than an absolute rule. Someone living in a city with extremely high housing costs may find it nearly impossible to keep essential expenses below half of their take-home income. The useful part is seeing how much of your income is already committed before discretionary spending begins.
Use around 30% for things you want
The wants category covers spending that improves your lifestyle but isn’t strictly necessary. Restaurants, vacations, entertainment, streaming subscriptions, hobbies, upgraded electronics, nonessential shopping, and other discretionary purchases usually belong here. With $4,000 in monthly take-home income, the framework would allow approximately $1,200 for wants. This doesn’t mean you should force yourself to spend the entire amount. It’s simply an upper-level guideline that creates space for enjoying your money while maintaining other financial priorities. The category can also reveal where seemingly small purchases accumulate. A $15 subscription might not feel significant, but several subscriptions combined with frequent restaurant meals, delivery fees, shopping, and entertainment can consume hundreds of dollars without any individual purchase appearing excessive. Instead of feeling guilty about every discretionary purchase, the 50/30/20 approach gives you one larger boundary. If your total wants remain within a level that works for your finances, you have flexibility to decide what is actually worth spending on.
Direct about 20% toward your financial future
The final 20% is generally dedicated to savings, investments, and paying down debt beyond required minimum payments. Using the same $4,000 example, that would mean approximately $800 each month. Where that money should go depends on your situation. Building an emergency fund may be the immediate priority for someone without savings. A person carrying expensive debt may choose to direct a significant portion toward repayment. Others might contribute to retirement accounts, invest for long-term goals, or save for a future home purchase. The important distinction is between minimum debt payments and additional repayment: minimum required payments are generally treated as needs because they must be paid, while additional payments that accelerate debt reduction can fit into the 20% financial-goals category. You also don’t necessarily need to divide this portion equally among every goal. Financial priorities change over time. You might spend several months building emergency savings, then redirect that same monthly amount toward another goal once your target has been reached.
Adjust the percentages to fit your real life
The biggest mistake is treating 50/30/20 as a financial law. It’s a framework, not a test you either pass or fail. A household spending 60% of its income on necessities isn’t automatically irresponsible, particularly if housing, childcare, healthcare, or transportation costs are unusually high. Someone with a high income might be able to save substantially more than 20%, while a person dealing with a temporary financial setback may need to save less until their situation improves. Start by calculating your current percentages rather than immediately trying to force them into the formula. If your needs consume 65%, wants take 25%, and savings receive 10%, you now have a clear picture of where you stand. From there, look for realistic adjustments. Perhaps you can reduce discretionary spending, renegotiate recurring expenses, increase income, or gradually increase savings by a few percentage points. The value of the 50/30/20 budget isn’t that the numbers are universally perfect. It’s that three simple categories can turn a confusing collection of transactions into a financial plan you can actually understand and use.